
NetBenefits - Fidelity at Work
- Rating
- 4.0
- Downloads
- 1.00M
- Content Rating
- Everyone
NetBenefits - Fidelity at Work - Screenshots
Pros
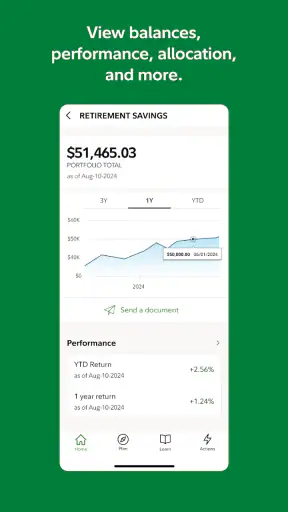
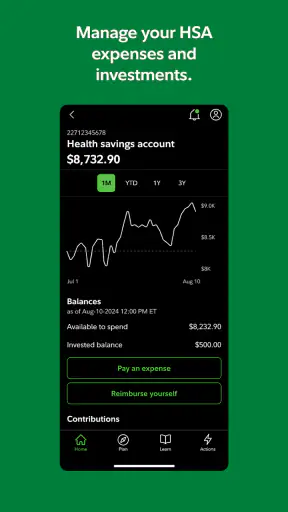
- Quick access to retirement balances and contribution details.
- Supports secure biometric login on compatible devices.
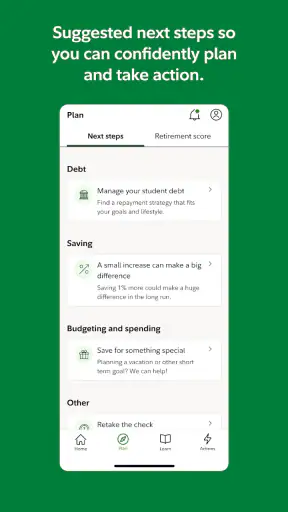
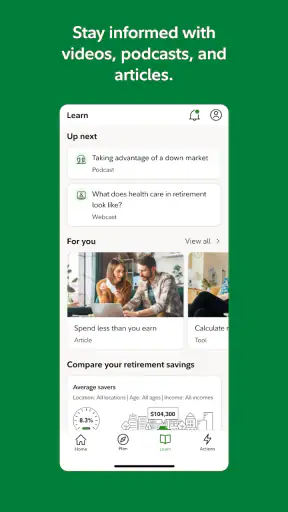
- Provides useful retirement planning and savings calculators.
- Makes it easy to review investment performance and account activity.
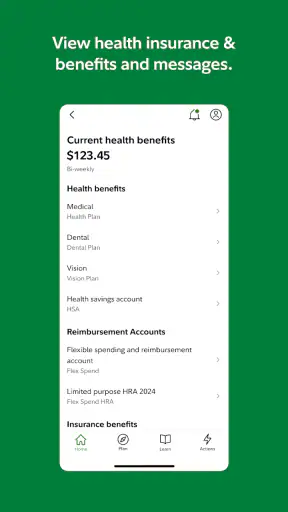
- Offers access to workplace benefits from one mobile dashboard.
Cons
- Some features depend on your employer’s available benefit plans.
- Investment details may be difficult for beginners to interpret.
- Certain account changes may require using the desktop website.
- App performance can vary during market activity or maintenance.
- Not all Fidelity services are available through the workplace app.
NetBenefits - Fidelity at Work - Description
- App Name
- NetBenefits - Fidelity at Work
- Package Name
- com.fidelity.wi.activity
- Developer
- Fidelity Investments
- Category
- Finance
- Last Updated
- Apr 24, 2013
- Version
- 4.35.2
Managing a workplace retirement account is usually something I postpone until I have a specific reason to check it. A contribution change, a new job, a benefits question, or a quick look at long-term savings can suddenly make it important. NetBenefits - Fidelity is built for those moments, giving Fidelity workplace account holders a mobile way to review and manage their information rather than waiting until they are back at a computer.
I tested it with a practical question in mind: does it make financial housekeeping easier when life is busy, and does it remain sensible when a phone or tablet is shared at home? My answer is mostly yes, provided each person keeps a clear boundary around their own account. This is a focused personal finance app, not a household budgeting dashboard, and that distinction shapes almost every part of the experience.
Developed by Fidelity Investments, the free app sits in the Finance category and carries an Everyone age rating. Its average rating is 4.0 from roughly 25 thousand ratings, with more than 7 thousand written reviews and over a million installs. Those figures suggest a widely used tool with a generally positive reception, although not one that avoids all frustration. The current release is version 4.35.2, and it requires iOS 12 or later.
Using it around a shared household
A useful companion for one person’s workplace account
The clearest use case is simple: I want to check my Fidelity workplace accounts while away from my desk. The app’s purpose is not to replace every financial service I use. It is there to put workplace-account information and related management tasks within reach when opening a laptop feels excessive.
That makes it handy during ordinary household routines. Imagine one partner preparing a monthly budget while the other wants to confirm a workplace contribution or review an account balance. NetBenefits - Fidelity can support the account owner’s part of that conversation, but it does not turn both people into joint users of the same financial workspace. Each person should treat the app as a private doorway to their own Fidelity information.
This matters on a shared tablet. A family might use one device for streaming, schoolwork, shopping, and finances, but the app should not be approached like a shared calendar. The person whose account is open should be the person making decisions, checking details, and ending the session. If another household member needs to understand a retirement choice, I would discuss the screen together without handing over permanent access to the account.
The best shared-device habit is to separate conversation from credentials. A partner can help compare a household plan or remind someone to review a workplace benefit, but the account owner should enter authentication details and approve account changes personally. That small distinction reduces confusion about whose information is being viewed and who is responsible for an action.
What it does well in an everyday scenario
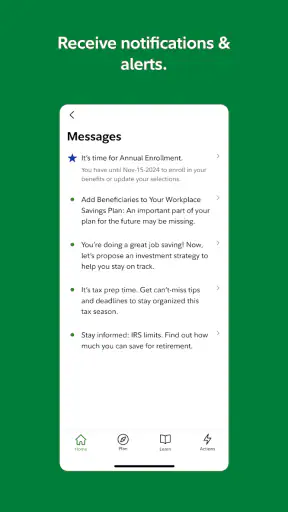
Consider a worker who receives a reminder to review workplace savings during a lunch break. Instead of waiting for a desktop session, they can open the app, inspect the relevant account area, and decide whether a follow-up is needed. The value is less about constant monitoring and more about removing the delay between remembering a financial task and getting started.
I also find the mobile format useful when a person is coordinating a household decision but does not want to expose every account detail. For example, someone can privately check their workplace account before discussing how much room the household has for a planned expense. That keeps the conversation informed without making the phone itself a communal financial file.
Still, I would not use it as the only place to understand a complicated benefits decision. A small screen encourages quick checks, while retirement and workplace choices sometimes deserve slower reading and careful comparison. The app is strongest for access and routine management; a larger screen or direct assistance may be more comfortable when the decision has several consequences.
Where the household model stops
NetBenefits - Fidelity is not a general-purpose family finance organizer. I would not choose it to track groceries, split bills, combine several banks, or create a shared spending plan. Those jobs belong to budgeting apps, banking tools, or a spreadsheet designed for multiple contributors.
It is also not the right answer when the household needs one shared view of every person’s retirement provider. A couple may have accounts with different employers or financial companies, and this app’s usefulness naturally centers on Fidelity workplace accounts. In that situation, it can still serve one partner well, but it will not replace a broader planning method.
This limitation is actually helpful because it keeps the purpose clear. The app does not ask me to turn a workplace account into a family control panel. It gives the individual account holder a direct mobile route to their own information. For a household, that means coordination happens around the app rather than inside a shared workspace.
Setup, boundaries, and coordination
Start with the account owner’s routine
When I set up a finance app, I prefer to decide in advance what I will use it for. With this one, a sensible first goal is a short list: check workplace-account information, review relevant account activity, and handle occasional management tasks. That approach prevents the app from becoming another notification-heavy destination that I open without a purpose.
On a shared device, I would install it under the account owner’s profile if the device supports separate user spaces. If it does not, I would be especially careful about who uses the device immediately before and after a session. The important boundary is not the household relationship; it is the separation between one person’s authenticated financial information and everyone else’s everyday access to the device.
I would also avoid treating a saved login as a convenience that automatically suits the whole household. A phone may be physically shared, but a workplace account remains personal. Before letting someone else use the device, I would close the session and confirm that account details are no longer visible. This is basic practice, yet it is easy to skip when a person is moving quickly between apps.
Why quick access needs deliberate checking
Mobile convenience can create a subtle risk: I may be tempted to make a change simply because the app makes the account available at an emotional moment. A market headline, a difficult month, or a conversation about bills can push someone toward an impulsive decision. I think the better workflow is to use the app to gather the relevant information, then pause before changing an important workplace setting.
For a household, that pause also improves coordination. If a decision affects expected savings or take-home pay, the account owner can first understand what is being changed and then explain the household impact. The other person can contribute questions without taking over the account. This is more respectful and more practical than passing a logged-in phone around.
One non-obvious advantage of this approach is that it creates an audit trail in your own memory: you know why you opened the app, what you checked, and whether you actually completed a task. I recommend writing down the follow-up question when the information is not clear instead of repeatedly reopening the same page. That keeps the app from becoming a substitute for understanding.
Coordinating without mixing accounts
Couples often need to coordinate retirement planning even when they do not share accounts. NetBenefits - Fidelity works well as one input into that discussion. Each person can review their own workplace information, then bring only the necessary figures or decisions to the household conversation. This preserves privacy while still allowing joint planning.
For example, one partner might be responsible for checking whether a workplace contribution is still aligned with the household plan, while the other tracks monthly expenses elsewhere. The app handles the first responsibility, not the second. Keeping those roles separate makes it easier to see which question belongs to Fidelity and which belongs to the household budget.
I would not ask a teenager or an uninvolved relative to “help” by navigating the account unless the account owner is present and comfortable with every step. Financial familiarity is not the same as authorization. The app’s straightforward mobile access is useful precisely because it puts control close to the account owner, so that control should not be casually delegated.
When a computer or another tool is better
The phone is convenient for a quick review, but I prefer a larger screen when I need to read several pieces of information side by side or think through a longer-term choice. A browser-based account experience may be more comfortable for detailed research, while NetBenefits - Fidelity is the better companion when I need access during the day.
A separate budgeting app is better for combining workplace income with rent, utilities, debt payments, and shared spending. A financial planner may be more appropriate for questions that depend on a complete household picture. The mobile app should be judged as a workplace-account tool, not criticized for refusing to become something broader.
Age, trust, and responsible access
Why an Everyone rating does not make it a children’s finance app
The Everyone content rating means the app is presented for a broad audience, but that should not be confused with suitability for unsupervised financial use by children. Workplace accounts belong to the adults who hold them, and the consequences of viewing or changing financial information are different from those of using an ordinary household app.
I would be comfortable explaining the general idea of workplace savings to an older child, showing how adults organize long-term goals, or discussing why account privacy matters. I would not give a child independent access to an adult’s authenticated session simply because the app itself has a general age rating. The responsible boundary comes from the account and the household, not just the label in the app store.
This is also relevant for older relatives who may need help with technology. Assistance can be valuable, but I would let the account holder remain physically present, enter sensitive credentials themselves, and make the final decisions. If the person cannot confidently tell what is happening on screen, the safer choice is to slow down and seek appropriate support rather than turning a helper into an unofficial account manager.
Trust on a device used by several people
Shared-device trust is more complicated than simply knowing everyone in the home. A guest may borrow the phone, a child may use the tablet, or a repair shop may handle the device. I would treat each transition as a reason to close the financial session. The goal is not suspicion; it is to avoid accidental exposure when the device changes hands.
Another useful habit is to discuss the app’s role before a financial disagreement occurs. If both partners understand that one person owns the account and the other is a discussion partner, there is less pressure to share access during a tense moment. That is a practical household rule, not a technical feature, and it makes mobile finance easier to manage responsibly.
I also recommend avoiding screenshots of account pages for household planning unless there is a clear reason to keep them. A screenshot can outlive the conversation, appear in a shared photo area, or remain on a device that someone else uses. Reading out the needed information or recording a general planning note is often safer than creating another copy of sensitive details.
Trusting the app without surrendering judgment
Fidelity Investments is a recognizable developer, and the app’s scale gives me confidence that it is intended for serious workplace-account use rather than casual financial entertainment. Even so, trust in the developer does not remove the need to review each screen carefully. I would check the account context before acting, especially when more than one workplace account or benefit area is available.
The app’s 4.0 average is reassuring but not a guarantee that every person will find the experience smooth. Finance apps can feel excellent for one task and awkward for another, particularly when an employer’s available benefits determine what appears in the account. I would evaluate it by whether it helps with my specific Fidelity workplace needs, not by the rating alone.
Version 4.35.2 indicates that the app is actively maintained as a current product, while the iOS 12 minimum makes it accessible to users who have not moved to the newest operating system. That is useful for households with an older compatible device, although I would still keep the device itself updated whenever possible and avoid using a device that no longer receives security maintenance.
My household verdict
Who I would recommend it to
I would recommend NetBenefits - Fidelity to a Fidelity workplace-account holder who wants practical mobile access and does not need a full household budgeting system. It is particularly useful for someone who checks financial information in short gaps during the day, coordinates savings decisions with a partner, or wants to avoid being tied to a desktop for routine account management.
It also suits households that value clear account ownership. One person can use the app privately, bring relevant information into a shared planning conversation, and keep the actual account session under their control. That arrangement is less flashy than a joint dashboard, but it is often the cleaner option for workplace benefits.
The free price removes an obvious barrier to trying it, and the broad age rating makes it easy to find in a household app library. I would still frame the experience for adults as a personal finance responsibility, especially when the device is shared with children or guests.
Who should choose something else
I would skip it if my main goal were household expense tracking, account aggregation across many institutions, or collaborative bill management. The app is too specialized for those needs. I would also look elsewhere if I did not have a relevant Fidelity workplace account, because its value depends on that connection rather than on general financial education.
Someone who prefers to analyze retirement choices on a large screen may find the mobile format limiting. Likewise, a user who wants a family member to have standing access to all financial details should think carefully about whether a personal workplace-account app is the right model. A shared planning document or professional guidance may fit that situation better.
The practical conclusion
After using it, I see NetBenefits - Fidelity as a focused access tool rather than a complete financial command center. Its strength is putting workplace-account management into an everyday mobile routine. Its weakness is the same focus: it does not solve the wider problems of household budgeting, multi-provider planning, or shared financial administration.
For me, the winning workflow is simple. The account owner opens the app with a specific question, checks the relevant information, avoids rushed changes, and brings the household-level implications into a separate conversation. On a shared device, the session ends before the next person takes over. That combination of convenience and discipline is where the app earns its place.
If your needs match that workflow, the free app from Fidelity Investments is worth trying. It has reached over a million installs and has been available since April 24, 2013, so it is not an experimental newcomer. My final view is positive but measured: use it as a private workplace-account companion, not as a shared family wallet. With that boundary in place, it can make an otherwise easy-to-ignore part of adult life more manageable.
FAQ
What is NetBenefits - Fidelity at Work used for?
NetBenefits - Fidelity at Work is designed to help eligible employees manage workplace benefits from a mobile device. Depending on your employer’s plan, you may be able to review retirement savings, check account balances, monitor investments, view contributions, access statements, and make certain changes to your benefits. The exact tools available can vary significantly between employers and plan types.
Can everyone download and use NetBenefits - Fidelity at Work?
Anyone may be able to download the app, but access to its full features generally requires an eligible Fidelity workplace account or an employer-sponsored plan administered through Fidelity. You will normally need your NetBenefits login credentials, and some users may be asked to complete additional identity verification. If your employer uses another provider, the app may not support your benefits.
Is NetBenefits - Fidelity at Work safe for managing financial information?
The app is intended to protect sensitive workplace and financial information through account authentication and security features such as password protection, device verification, and, where supported, biometric sign-in. However, no digital service is completely risk-free. Use the official app store version, avoid public Wi-Fi when possible, keep your device updated, and never share your login or verification codes with anyone.
What can I do if I cannot sign in to the app?
If sign-in fails, first confirm that you are using the correct Fidelity username and password and that your internet connection is working. You can use the available account-recovery options to reset credentials or unlock access. Problems may also result from outdated app software, device settings, or employer-specific restrictions. If the issue continues, contact Fidelity workplace support through the official help options.
Does NetBenefits - Fidelity at Work charge a fee to download or use?
The NetBenefits - Fidelity at Work app is generally available to download without a separate purchase price, although standard mobile data charges from your carrier may apply. The app itself does not determine every cost connected with your workplace plan. Investment expenses, administrative fees, or other account charges can depend on your employer’s plan and the investments you choose, so review official plan documents carefully.


